 Watch · Europa Wire
While most other investors concentrate on making money in stocks over the next 20 days or weeks, long-term thinkers should focus on the next 20 years that lie ahead. Of course, it’s really hard to think that far into the future, but for today’s young investors, I do think that getting started early is key to unlocking the most power from long-term compounding. Indeed, stocks have been running hot of late and, like it or not, there’s going to be a down year every so often, perhaps when investors least expect it.
And while the path to a nice nest egg isn’t going to be a smooth ride higher, especially for those with a significant chunk of their wealth in equities, the important thing is where that nest egg winds up in 20 years’ time. If it takes extreme volatility and the odd plunge into a bear market, so be it. At the end of the day, investors must focus on the kinds of businesses with staying power to do well over a multi-decade timeframe.
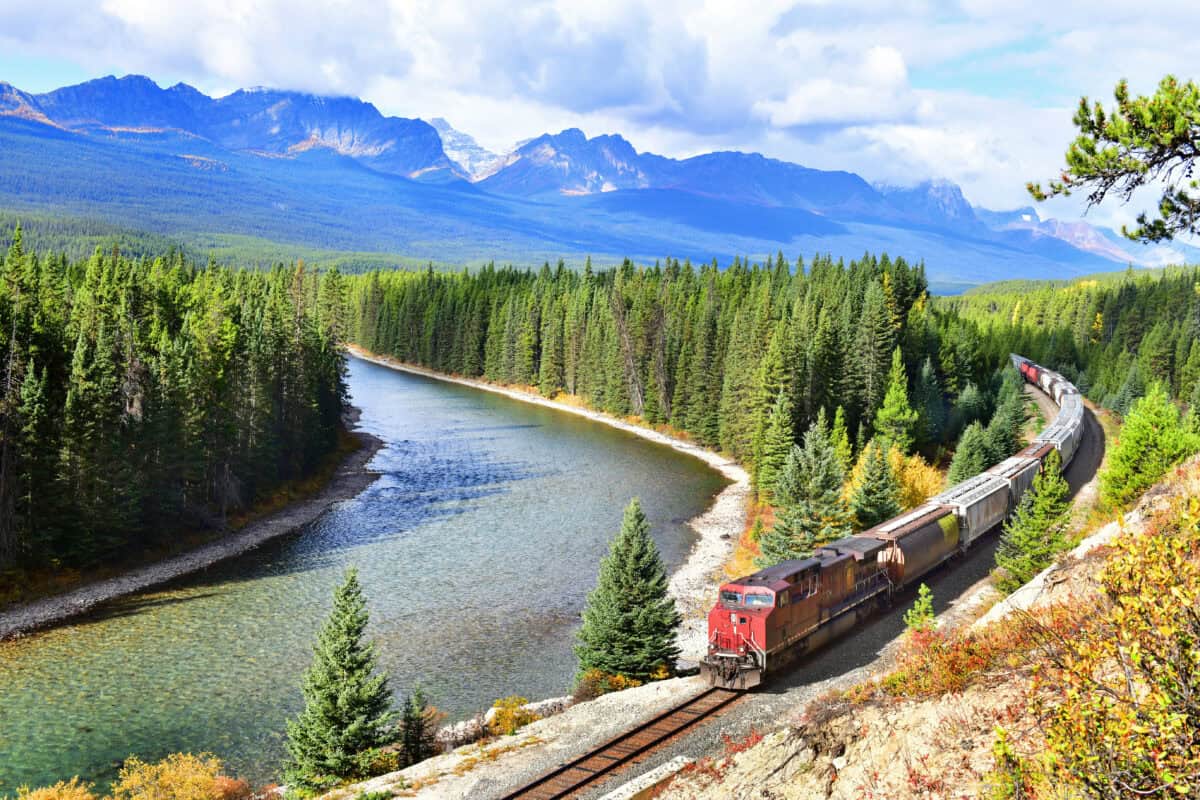
When it comes to dividend growers with wide economic moats and more in the way of cash flow predictability, I think that it’s tough to top the following pair of names, especially in today’s choppy market. Source: Getty Images CN Rail First up, we have CN Rail ( TSX: CNR ), a railway that’s probably going to continue to conduct business as usual in the next 10–20 years. Not a whole lot has changed about the railways since 2006.
And while I do think there are serious changes coming for the industry in the next two decades, my guess is that it’ll be changes that vastly enhance the operating economics of the railways. At the end of the day, physical infrastructure assets aren’t so easily replicable by the rise of AI and agents. While self-driving trucks and all the sort might rise as a credible challenger to CN Rail, it’s my view that self-driving trains, especially as more energy-efficient locomotives come to be, will continue to be the cheapest and timeliest way to get goods from A to B.
Add improvements in scheduling and other technologies underneath the hood, and I find the rails to offer wide-moat names to stick with for the long haul. The dividend growth icon has a nice 2.1% dividend yield and goes for a modest 21.8 times trailing price-to-earnings (P/E) multiple. CIBC CIBC ( TSX: CM ) is showing a bit of weakness after a red-hot two-year rally.
Things feel a bit toppy, but I think the weakness is more of an opportunity to buy, especially as CIBC looks to become one of the cheaper banks of the Big Six again. Today, the stock goes for 15.1 times trailing P/E with a 2.7% yield. Not bad considering the premium that banks commanded at around the peak.
Of course, the heavy mortgage book may be perceived as a risk, especially as rates rise. Still, the agentic AI opportunity and expansion into the U.S., I think, are secular drivers that are currently incredibly underrated at today’s price of admission. In my view, CIBC is a name to buy and hold for years, even decades, for the dividend, growth, and, of course, dividend growth potential.
Source: The Motley Fool Canada